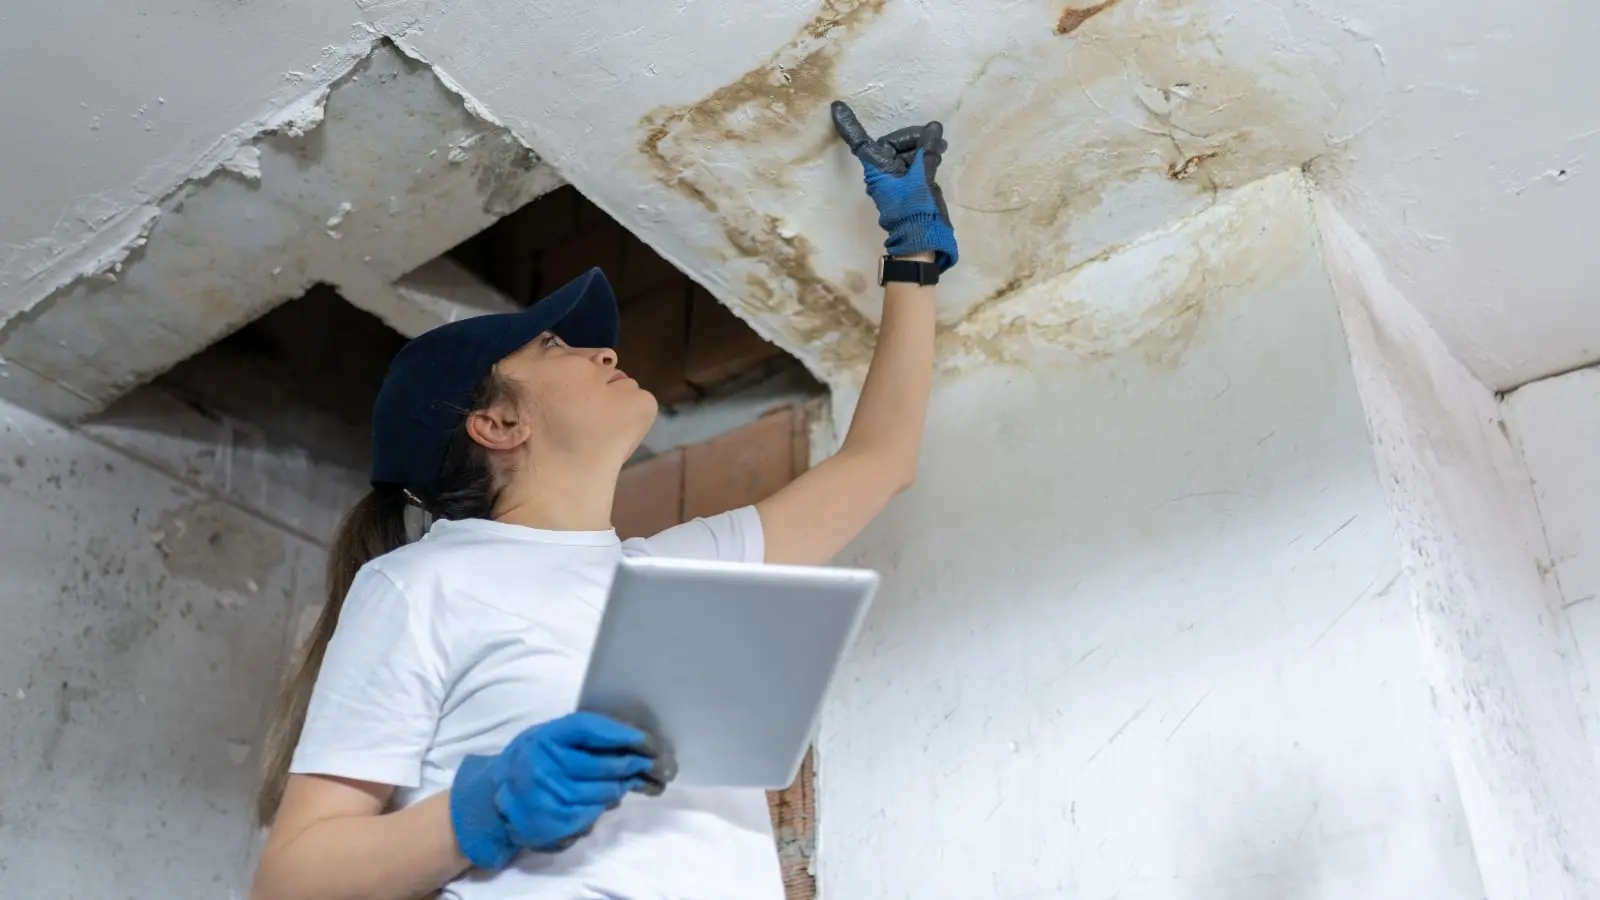
It depends on the source of the water
Whether insurance covers water damage depends mostly on the cause. Per the Massachusetts Division of Insurance, damage from a non-flood source, such as a burst pipe, falls under a standard homeowners policy, which usually covers damage that is sudden and accidental. Flood damage is another matter: the Division states that standard home insurance policies do not cover flood damage.
That single distinction explains most coverage surprises. A pipe that burst in the wall and a creek that rose into the basement can leave the same wet carpet, yet they sit in different insurance categories.
Your own policy has the final word. Read the water damage section, check the declarations page and ask your insurer or agent about anything unclear. Nothing here is a promise of coverage.
Common water damage causes and how they are usually treated
| Cause | Typical treatment under a standard policy | What to check |
|---|---|---|
| Burst pipe or failed supply line | Often covered if sudden and accidental | Whether the home was properly heated and occupied |
| Appliance failure such as a washing machine hose | Often covered if sudden | Policy wording on appliance leaks |
| Slow leak or long-term seepage | Often excluded as gradual damage | How long the leak went on and when it was found |
| Roof leak from a storm | Depends on cause and maintenance | Roof age and policy conditions |
| Flooding from a river, brook or heavy rain | Excluded from standard policies | Whether you carry a separate flood policy |
| Sewer or drain backup | Covered by flood policy only if a flood is the cause, or by an endorsement | Declarations page for a water backup endorsement |
This table is general guidance. Your policy and your insurer decide what applies to your loss.
Sewer backup and sump pump failure
Sewer and drain backups are a common surprise. The Division of Insurance explains that flood policies cover water that backs up through sewers or drains, sump pump discharge or seepage only when a flood in the area is the proximate cause.
A backup caused by a clogged line, with no flood, is not a flood policy matter. The Division's advice is to check your declarations page for a sump pump failure or water backup endorsement, which may provide some coverage. Many homeowners learn they lack it only after a loss, so look now.
If you are unsure whether your sump pump has coverage, call your agent and ask about the limit as well, since endorsements often carry smaller limits than the main policy.
Flood insurance is separate
Flood insurance is available through the National Flood Insurance Program and from private insurers. The Division lists the NFIP number as 877-336-2627 and publishes a list of licensed private flood insurers on its website.
Do not assume you need it only if you live next to water. The Division notes that standard policies exclude flood damage even away from oceans and rivers. Check your address on the FEMA Flood Map Service Center and talk with your agent about whether a flood policy makes sense. Our work in flood damage restoration often starts with homeowners who learned about this exclusion after a storm.
Questions to ask your insurer or agent
Coverage questions
- Does my policy cover sudden water damage from pipes and appliances?
- Do I have a sump pump failure or water backup endorsement, and what is the limit?
- Do I have flood coverage, and what is excluded?
- What do you need from me before mitigation or repair begins?
- How are gradual leaks treated under this policy?
- Who should I call to open a claim, and is there a deadline to report?
What to do while you wait for answers
Coverage questions can take time, and water damage does not wait. Photograph the damage, report the loss and begin water mitigation so the harm does not grow. The Division advises protecting the property from further damage where reasonably possible, and insurers generally expect homeowners to take sensible steps.
Keep every receipt for emergency work and keep damaged materials or photographs of them until the adjuster has seen them. If your insurer asks for documentation, a restoration company can provide moisture readings and a written scope.
Ask your insurer whether it wants to inspect before work starts, and whether it has a preferred way to receive photos. Write down the date of every call. If the claim is large or disputed, a short written timeline of what happened and when often helps everyone stay on the same page, and it costs nothing but ten minutes of your time.
Common mistakes that cause coverage surprises
Most coverage disputes grow out of a handful of predictable mistakes. People assume flood damage is included, never read the sublimits for appliance leaks or sewer backup, and wait weeks before reporting. Some throw away damaged materials before anyone has seen them.
Another mistake is letting a contractor answer the coverage question. A restoration company can describe what it sees and provide readings, but only your insurer decides what the policy pays. If anyone promises approval, treat that as a warning sign.
A better habit is to read the water section of your policy once a year, confirm whether you carry an endorsement for backup or sump failure, and store a copy of the declarations page where you can find it in a hurry.
Massachusetts resources for Framingham homeowners
The source type for this section is the Massachusetts Division of Insurance, the state regulator. Its Consumer Services Unit answers coverage questions at 617-521-7794 and takes complaints, and its flood pages explain how standard and flood policies differ.
The Division also lists a licensed private flood insurer directory, and FEMA operates the NFIP. If you live just outside the city, the same state resources apply in Natick and Sudbury, since insurance rules in Massachusetts are set at the state level.
Local permits for rebuild work are a separate question, handled by each town's building office. In Framingham that is Inspectional Services at 508-532-5500.
Not sure what your loss means for coverage?
Call the 24/7 line to start mitigation, and keep your insurer in the loop.
Frequently asked questions
Per the Division of Insurance, most policies cover sudden and accidental burst pipes, usually when the home was properly heated and occupied. Confirm with your insurer, since policy wording differs.
Standard homeowners policies do not. Flood coverage comes from the National Flood Insurance Program or private flood insurers as a separate policy.
It depends. Flood policies cover backups only when a flood is the underlying cause. A water backup endorsement on a homeowners policy may provide some coverage, so check your declarations page.
Often not. Gradual leaks and neglect are commonly treated differently from sudden damage. Your insurer will look at how long the leak went on.
The Division of Insurance Consumer Services Unit at 617-521-7794 answers questions about coverage and the claims process.
Water still spreading? Call (508) 446-9244 and a dispatcher answers around the clock.